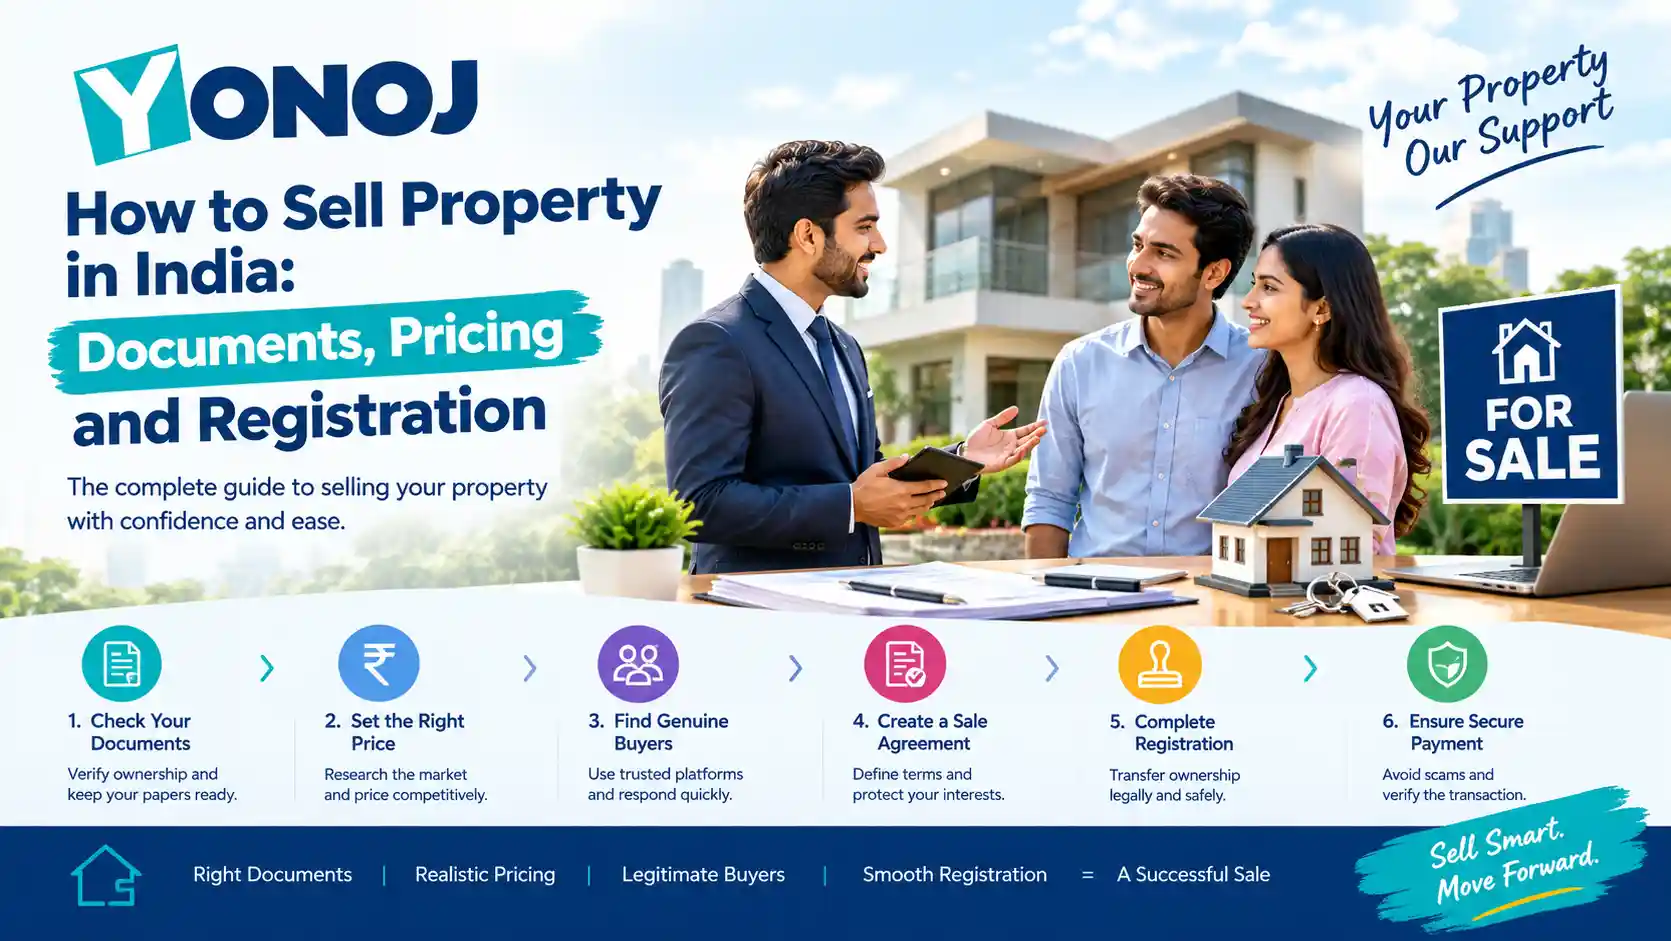
Selling a property in India involves more than finding a buyer and agreeing on a price. Whether you are selling a flat, independent house, residential plot, or commercial property, you need to prepare the right documents, determine a fair market value, negotiate carefully, and complete the legal transfer process.
Many property owners feel confused about where to start, which documents are required, how to find genuine buyers, and what happens during property registration. A lack of preparation can cause delays, disputes, or unexpected expenses.
If you are researching how to sell property in India, this step-by-step guide will help you understand the process, prepare your property for sale, and make informed decisions from the initial valuation to the final registration.
1. Check Your Property Ownership Documents
Before advertising your property, verify that your ownership documents are complete and consistent. Buyers and their legal advisers may examine these records before proceeding with the transaction.
The exact documents required depend on the property type, location, ownership history, and applicable state rules.
Commonly relevant documents include:
- Title deed or sale deed: Evidence of ownership and the previous transaction.
- Previous ownership documents: Earlier title records, where relevant.
- Encumbrance Certificate (EC): Records certain registered transactions or encumbrances for the specified period; it does not independently guarantee that a property has a clear title.
- Property tax receipts: Evidence of property tax payments.
- Approved building plan: Relevant for flats, houses, and other constructed properties.
- Occupancy or completion certificate: Where applicable.
- Registration and mutation records: Relevant records maintained by the registration or local revenue authorities.
- Identity and PAN documents: Required for applicable transaction and tax formalities.
- Society or association documents: Where applicable to an apartment or housing society.
- Loan-closure and release documents: If the property was mortgaged and the loan has been repaid.
For inherited or jointly owned property, additional documents may be required to establish the rights of all owners and the authority to sell.
Practical tip: Ask a property lawyer to review your title documents before you finalise a buyer, especially if the property has an inheritance history, multiple owners, or unresolved legal issues.
2. Determine the Right Selling Price
Setting a realistic price is one of the most important steps in selling property. An excessively high price may discourage genuine buyers, while an unnecessarily low price can reduce your potential return.
Start by researching comparable properties in the same locality.
Factors that influence property value
- Location and neighbourhood development
- Property type, size, and usable area
- Age and overall condition of the building
- Floor level, parking, and available amenities
- Road access, public transport, schools, and hospitals
- Recent comparable sales, where reliable information is available
- Current demand and supply in the local market
- Legal status and availability of required approvals
Compare properties with similar features rather than relying only on advertised prices. Listing prices may differ from the final prices at which properties sell.
You can also consult local property professionals or obtain an independent valuation when appropriate.
Should you keep room for negotiation?
You may set an asking price that allows reasonable negotiation, but avoid adding an arbitrary amount simply because you expect buyers to bargain.
A well-supported asking price, backed by comparable properties and accurate documents, can help make discussions more productive.
3. Calculate the Costs Before Selling
Before agreeing to a final price, estimate the expenses that could affect the amount you receive.
Depending on the transaction, these may include:
- Brokerage or professional service fees, if applicable
- Outstanding home loan or mortgage repayment
- Legal review and documentation expenses
- Applicable taxes on capital gains
- TDS-related compliance, where applicable
- Charges for obtaining certificates or completing formalities
- Other agreed transaction costs
Tax treatment depends on factors such as the date and cost of acquisition, improvement expenses, holding period, property type, seller’s tax status, and applicable law.
For certain transfers of immovable property involving resident sellers, Section 194-IA of the Income-tax Act has TDS requirements when the relevant threshold is met. Rules may differ for non-resident sellers and other circumstances. Verify the current requirements with a qualified tax professional before completing the transaction.
Do not assume that the amount received from the buyer is automatically your final profit. Calculate your likely net proceeds after considering relevant expenses and tax obligations.
4. Prepare Your Property for Potential Buyers
A clean, well-presented property can create a better first impression and help buyers assess its condition.
Before arranging viewings:
- Clean the rooms, kitchen, bathrooms, and balconies.
- Repair minor defects where it is practical.
- Check plumbing, electrical fittings, doors, and windows.
- Improve lighting and ventilation.
- Remove unnecessary clutter.
- Keep available property documents organised.
- Take clear photographs of the rooms and exterior.
If the property is rented, review the existing tenancy agreement and understand the tenant’s rights and the terms that may affect the sale.
Avoid spending heavily on renovations without assessing whether the likely improvement in saleability justifies the expense.
5. Advertise Your Property and Find Genuine Buyers
Once the property is ready, prepare a clear advertisement that explains what you are selling.
Include details such as:
- Property type and locality
- Built-up or carpet area, as applicable
- Number of bedrooms and bathrooms
- Floor number and lift availability, where relevant
- Parking and amenities
- Age and condition of the property
- Asking price
- Occupancy status
- Important features and nearby facilities
Use recent photographs and provide accurate information. Do not exaggerate the area, amenities, approvals, or expected rental income.
You can also use online directories and local service platforms to explore relevant property professionals, legal advisers, or other services. For local business and service discovery, visit Yonoj.net.
How to handle buyer enquiries
Respond clearly to questions about the price, location, ownership, maintenance charges, and availability.
Before sharing sensitive documents, consider redacting unnecessary personal information. You can provide appropriate copies to a serious buyer or their lawyer during due diligence.
Verify a buyer’s identity and seriousness before investing significant time in negotiations. Avoid accepting suspicious payment arrangements or paying unexpected fees to release supposed funds.
6. Negotiate and Agree on the Terms
Once you find an interested buyer, discuss the price and the conditions of the sale.
Apart from the final price, clarify:
- The amount and timing of the advance payment
- The proposed date for signing the sale agreement
- The expected completion and registration date
- How any outstanding loan will be settled
- Responsibility for agreed transaction expenses
- When possession will be handed over
- What happens if either party does not fulfil the agreement
Record the agreed terms in a properly drafted agreement. The document should accurately describe the property, payment schedule, parties, deadlines, and applicable conditions.
Have a qualified property lawyer review the agreement before signing, especially when the transaction involves a loan, multiple owners, tenants, or complicated title records.
Avoid relying solely on verbal promises.
7. Understand the Property Sale Agreement
A sale agreement generally records the terms under which the buyer and seller intend to complete the transaction. The exact legal requirements and consequences depend on the document and applicable law.
Important details may include:
- Full names and details of the parties
- Property description and identification details
- Agreed sale consideration
- Advance or earnest money
- Payment milestones
- Time limit for completion
- Responsibilities of the buyer and seller
- Conditions relating to loan clearance or document verification
- Default, cancellation, and dispute-resolution terms
- Possession arrangements
An agreement to sell is generally not a substitute for the registered conveyance or sale deed required to transfer ownership where registration is legally necessary.
Ensure that the documents are prepared and executed in accordance with the applicable legal requirements.
8. Complete Property Registration
Property registration is a key part of many property sales in India. The transfer generally requires an appropriate sale deed or conveyance document, execution by the relevant parties, and registration with the competent Sub-Registrar where required by law.
The process and associated charges vary by state and transaction.
Typical registration steps
Step 1: Prepare the sale deed. Have the deed drafted or reviewed to ensure that the property description, consideration, ownership details, and terms are accurate.
Step 2: Verify the applicable stamp duty. Stamp duty depends on state law and other relevant factors, which may include the property value and applicable valuation rules.
Step 3: Arrange the required documents. The Sub-Registrar may require identity documents, photographs, PAN details where applicable, title records, payment evidence, and other prescribed documents.
Step 4: Complete execution and registration. The parties and any required witnesses must follow the applicable registration procedure and appear before the competent authority as required.
Step 5: Retain the registered document. Keep the registered deed and transaction records safely. Complete any relevant mutation or municipal record updates according to local requirements.
Before the appointment, confirm the current procedure, fees, document list, and appointment requirements with the relevant state’s registration department or Sub-Registrar office.
9. Handle Payment Safely
Property transactions involve substantial amounts, so payment verification is essential.
Follow these precautions:
- Prefer traceable banking channels.
- Confirm that funds have actually been credited to the correct account.
- Do not rely only on screenshots or payment confirmation messages.
- Avoid signing documents that falsely acknowledge receipt of money.
- Record the payment schedule and amounts accurately.
- Keep copies of receipts and relevant bank records.
- Coordinate loan repayment and release of any mortgage with the lender, where necessary.
If payment is being made in stages, ensure that the sale agreement clearly records the schedule and the consequences of delayed or incomplete payment.
Do not hand over possession or execute documents contrary to the agreed terms without obtaining appropriate legal advice.
10. Complete Handover and Follow-Up Formalities
After the agreed payment and registration requirements have been completed, arrange possession according to the sale agreement.
Depending on the property, the handover may include keys, access cards, parking details, available warranties, utility information, and relevant maintenance records.
Also consider the following:
- Record the possession date.
- Keep copies of the registered sale deed and payment evidence.
- Settle or document agreed outstanding utility and maintenance charges.
- Inform the relevant housing society or association where necessary.
- Complete applicable municipal or revenue record updates.
- Preserve documents needed for income-tax reporting.
If the property was mortgaged, confirm that the relevant loan and security-release formalities have been completed.
11. Common Mistakes to Avoid When Selling Property
Avoid these common mistakes to make the process smoother:
- Setting a price without researching the local market
- Ignoring title issues or ownership disputes
- Advertising inaccurate property details
- Failing to disclose relevant defects or legal matters
- Signing an agreement without understanding its terms
- Overlooking applicable stamp duty or tax obligations
- Accepting unverified payments
- Handing over possession without following the agreed terms
- Forgetting post-registration record updates
A little preparation can reduce avoidable delays and help both parties understand their responsibilities.
Frequently Asked Questions
1. How can I sell property in India?
Start by checking your ownership documents, researching the market price, preparing the property, advertising it, and finding a genuine buyer. Negotiate the terms in writing, complete the required sale deed and registration formalities, and follow applicable tax and record-update requirements.
2. What documents are required to sell property in India?
Commonly relevant documents include the title or sale deed, previous ownership records where necessary, property tax receipts, identity and PAN documents where applicable, and relevant approvals or certificates. Additional documents may be needed depending on the property, state, ownership history, and financing status.
3. How do I decide the selling price of my property?
Compare similar properties in the same locality, consider the property’s size and condition, review reliable market information, and seek a professional valuation if needed.
4. Is property registration mandatory when selling a property?
The applicable law generally requires registration of the sale deed or conveyance for a sale of immovable property where registration is required. Consult the relevant Sub-Registrar or a qualified property lawyer for your specific transaction.
5. Who pays stamp duty and registration charges?
The parties can address responsibility for these costs in their agreement, subject to applicable law. State-specific rules and the transaction terms determine the charges and their allocation.
6. Do I have to pay tax when I sell property in India?
A property sale may result in taxable capital gains. The tax treatment depends on the acquisition date, cost, holding period, applicable law, and other circumstances. Consult a tax professional to calculate your liability and determine whether any exemptions or deductions apply.
7. Can I sell a property that has an outstanding home loan?
It may be possible, but the outstanding loan and the lender’s requirements must be addressed. Coordinate the payment and mortgage-release process with the lender and obtain legal guidance before finalising the transaction.
8. How long does it take to sell property in India?
There is no fixed timeline. It depends on the location, asking price, buyer demand, documentation, financing, due diligence, and registration process. Having complete documents and a realistic price may help avoid unnecessary delays.
Final Thoughts
Selling property in India becomes easier to manage when you prepare the documents, research the market value, advertise accurately, and understand the legal process before accepting an offer.
Focus on three priorities: clear ownership documents, realistic pricing, and a properly documented transaction. Confirm state-specific registration requirements and consult qualified legal and tax professionals when needed.
If you are preparing to sell your property, use this guide as a starting point and explore Yonoj.net for local business and service discovery. With careful preparation and the right professional support, you can approach your property sale with greater confidence.